
Sawdust Signals – Vol. 1 Issue. 8 – The Show-Me-The-Order Edition
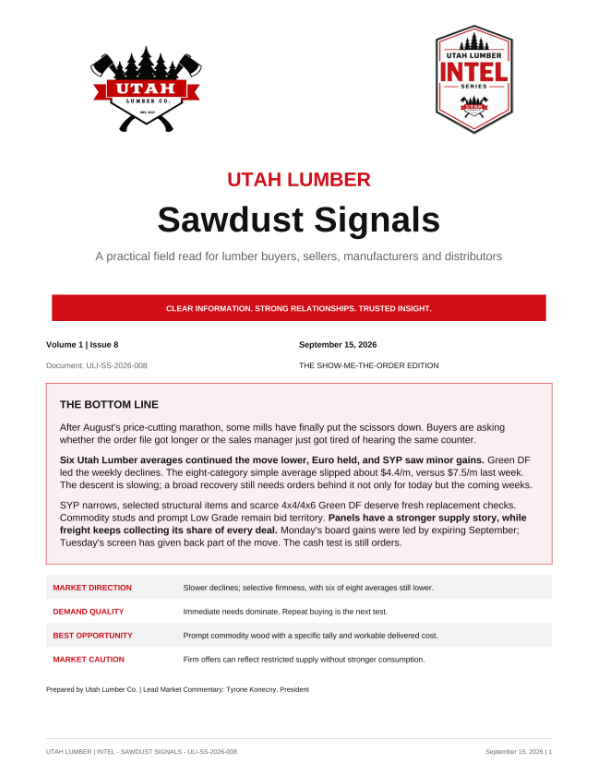
After August’s price-cutting marathon, some mills have finally put the scissors down. Buyers are asking
whether the order file got longer or the sales manager just got tired of hearing the same counter.
Six Utah Lumber averages continued the move lower, Euro held, and SYP saw minor gains. Green DF
led the weekly declines. The eight-category simple average slipped about $4.4/m, versus $7.5/m last week.
The descent is slowing; a broad recovery still needs orders behind it not only for today but the coming weeks.
Sawdust Signals – Vol. 1 Issue. 7 – The Counteroffer Hangover Edition
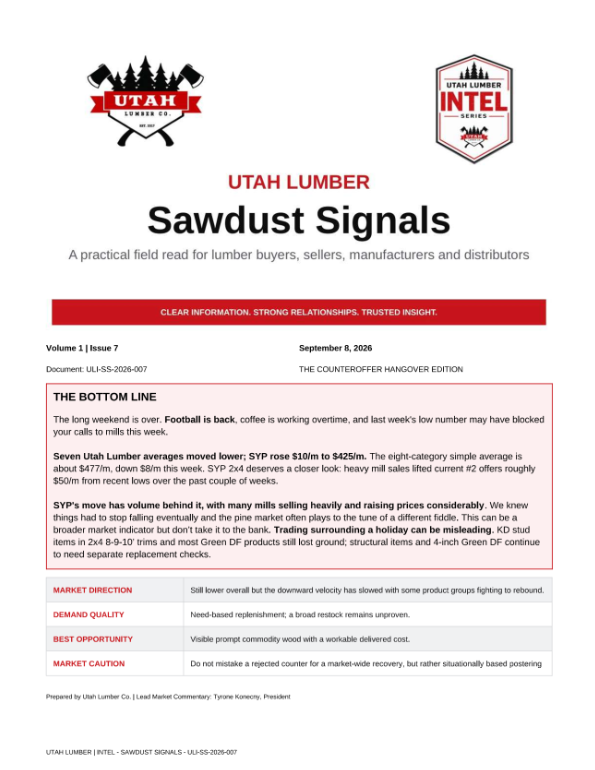
The long weekend is over. Football is back, coffee is working overtime, and last week’s low number may have blocked
your calls to mills this week.
Seven Utah Lumber averages moved lower; SYP rose $10/m to $425/m. The eight-category simple average is
about $477/m, down $8/m this week. SYP 2×4 deserves a closer look: heavy mill sales lifted current #2 offers roughly
$50/m from recent lows over the past couple of weeks.
Sawdust Signals – Vol. 1 Issue. 6 – The Clearance Aisle Edition
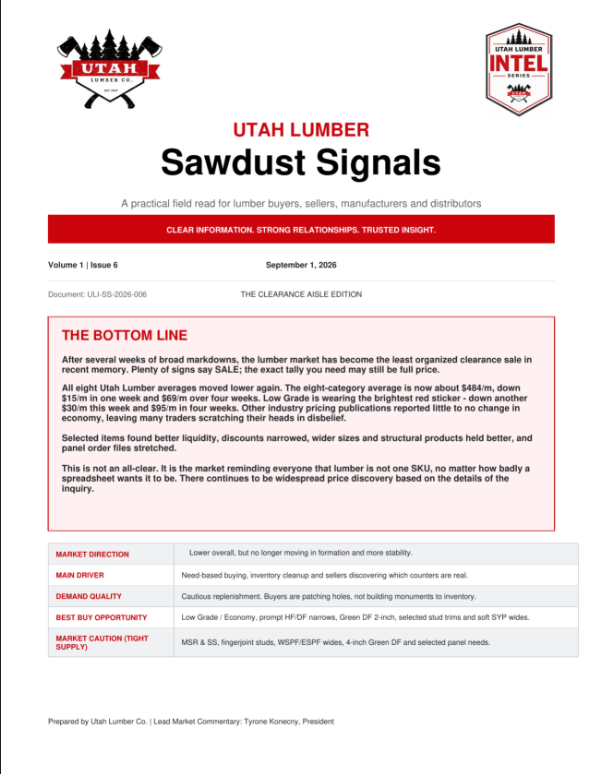
After several weeks of broad markdowns, the lumber market has become the least organized clearance sale in
recent memory. Plenty of signs say SALE; the exact tally you need may still be full price.
All eight Utah Lumber averages moved lower again. The eight-category average is now about $484/m, down
$15/m in one week and $69/m over four weeks. Low Grade is wearing the brightest red sticker – down another
$30/m this week and $95/m in four weeks. Other industry pricing publications reported little to no change in
economy, leaving many traders scratching their heads in disbelief.
Sawdust Signals – Vol. 1 Issue. 5 – The Counter Culture Edition
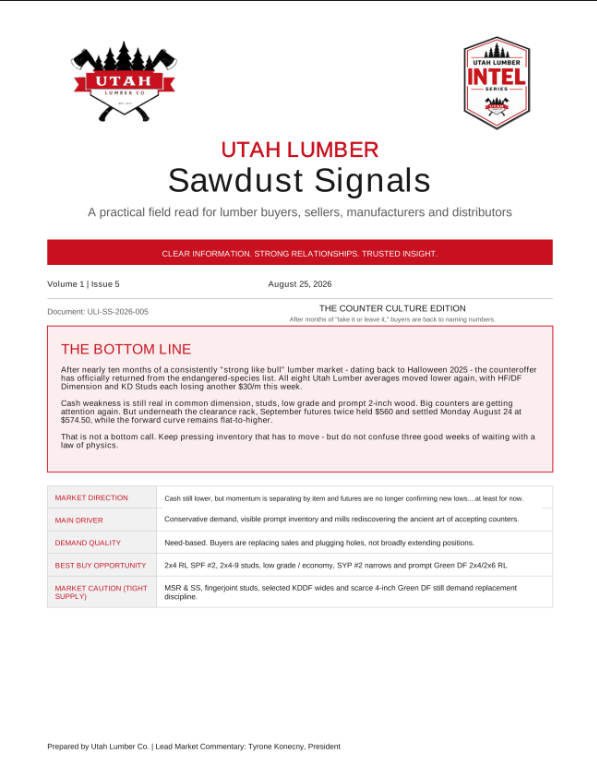
After nearly ten months of a consistently “strong like bull” lumber market – dating back to Halloween 2025 – the counteroffer
has officially returned from the endangered-species list. All eight Utah Lumber averages moved lower again, with HF/DF
Dimension and KD Studs each losing another $30/m this week.
Utah Lumber Intel Vol. 1 Issue 4– Sawdust Signals
The correction futures signaled is now firmly in cash. Every category in the Utah Lumber Market Averages moved
lower again this week, while broad framing benchmarks in all species continued to retreat.
Volume 1 | Issue 2 – Sawdust Signals
A practical field read for lumber buyers, sellers, manufacturers and distributors.
Cash is confirming the softer tone, but futures still lead price discovery. Positive cash basis and
nearby/deferred carry give buyers leverage without making every physical tally cheap. More producers are
taking sizeable counters to move on-ground inventory when volume and destination align; protected mills
are digging in. Press common 2-inch, Southern Pine and soft stud trims; protect real replacement risk.