
Sawdust Signals – Vol. 1 Issue. 13– The No-Heavy-Lifting Edition
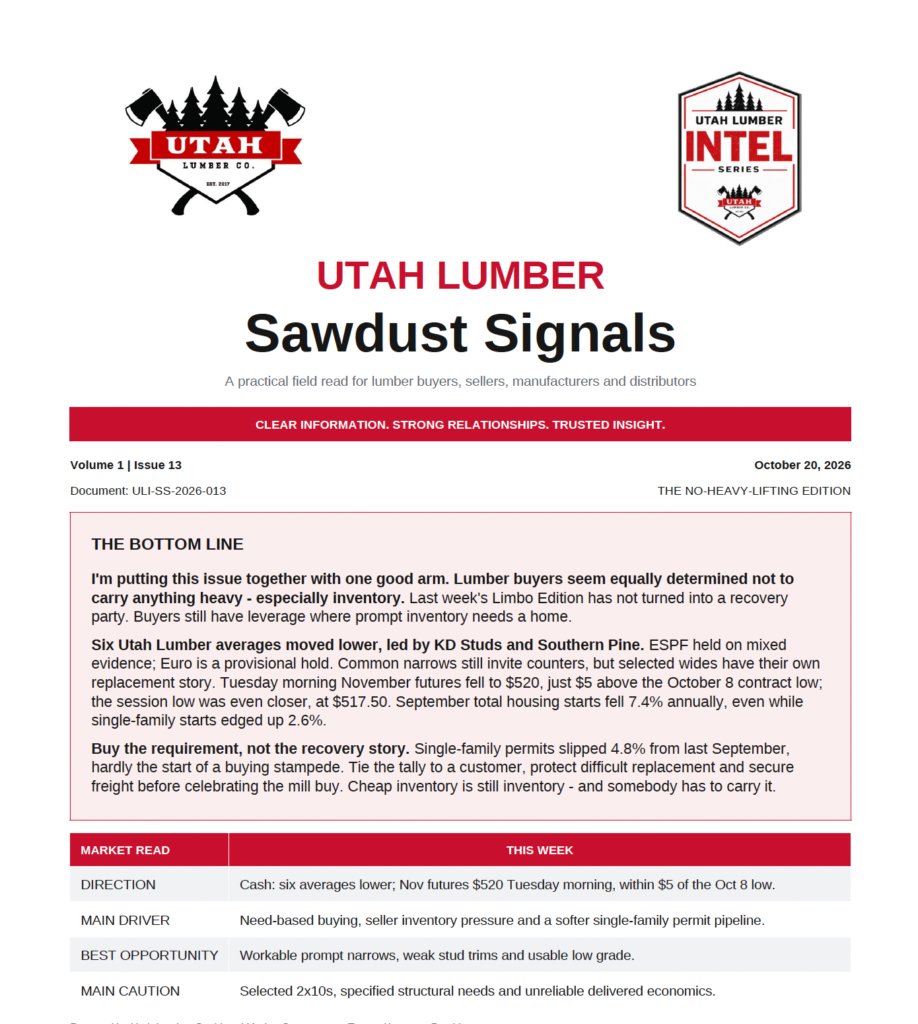
I’m putting this issue together with one good arm. Lumber buyers seem equally determined not to
carry anything heavy – especially inventory. Last week’s Limbo Edition has not turned into a recovery
party. Buyers still have leverage where prompt inventory needs a home.
Six Utah Lumber averages moved lower, led by KD Studs and Southern Pine. ESPF held on mixed
evidence; Euro is a provisional hold. Common narrows still invite counters, but selected wides have their own
replacement story. Tuesday morning November futures fell to $520, just $5 above the October 8 contract low;
the session low was even closer, at $517.50. September total housing starts fell 7.4% annually, even while
single-family starts edged up 2.6%.
Sawdust Signals – Vol. 1 Issue. 12– The Limbo Edition
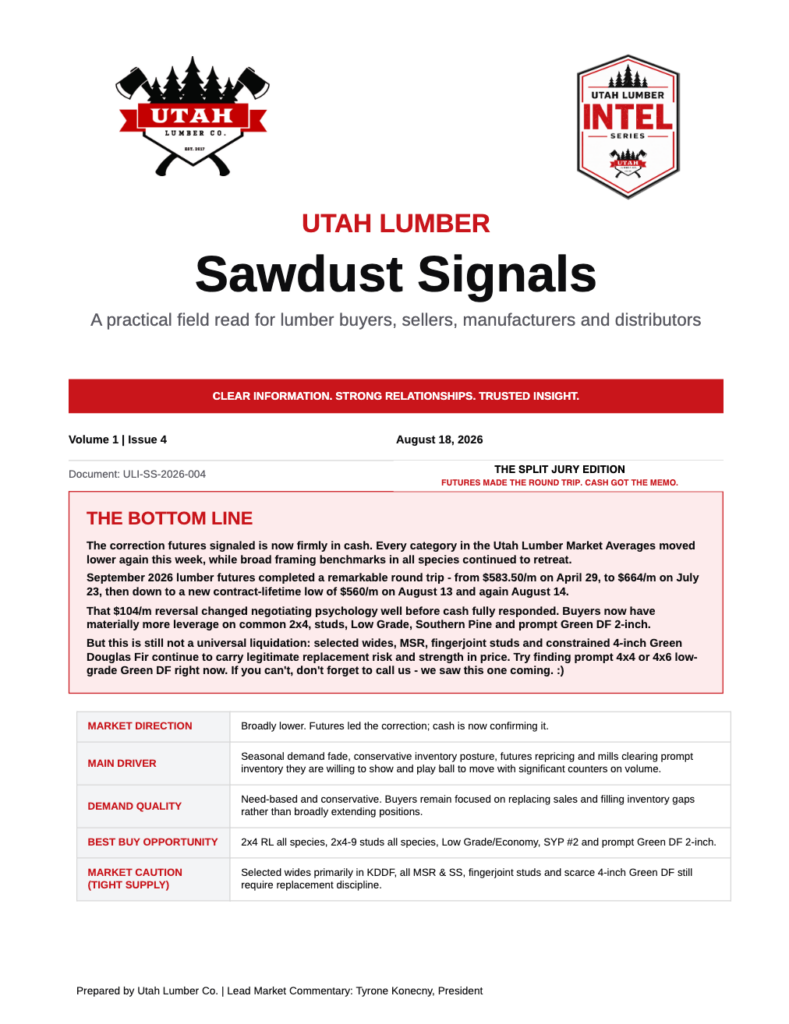
Some sellers are playing limbo. Some buyers are playing chicken. And a few tight items are still
playing hard to get. After roughly 90 days of decline, the answer to “How low can it go?” depends on which
supplier you cal, what is sitting in the yard and how badly it needs to move.
We held the benchmarks because the trading range is as much of a moving target as a drunk trying to play
darts blindfolded! Where will we find a floor…or a shelf…or a life preserver? A mil protecting replacement,
a desperate wholesaler cleaning up a high costed position and a seler not in distress may quote very different
numbers for the same item.
Sawdust Signals – Vol. 1 Issue. 11 – The Shipping & Handling Edition
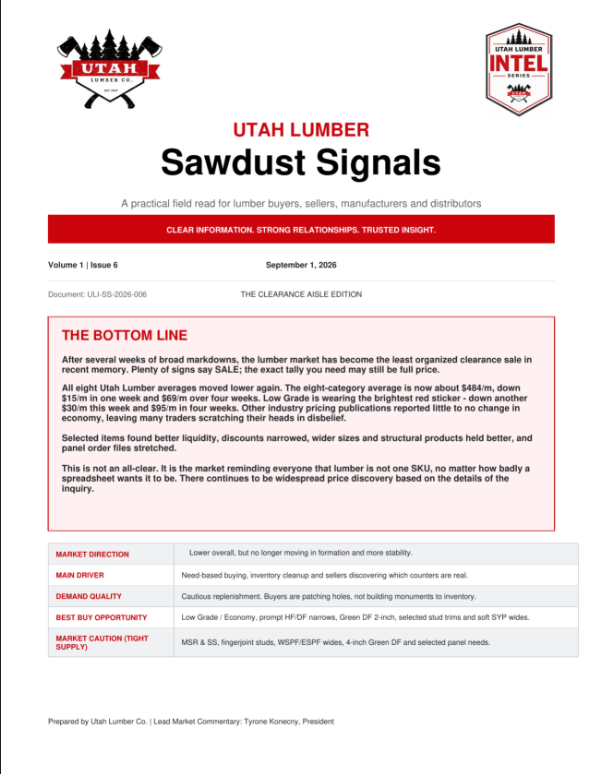
Last week three categories found the brake pedal. This week all eight are rolling downhill again. Utah
Lumber averages fell $5-$15/MBF. The simple eight-category average is $449.38/MBF, down $8.13 from last
week. The showroom still has plenty of shoppers. The checkout line remains manageable.
Sawdust Signals – Vol. 1 Issue. 10 – The “Just Looking” Edition
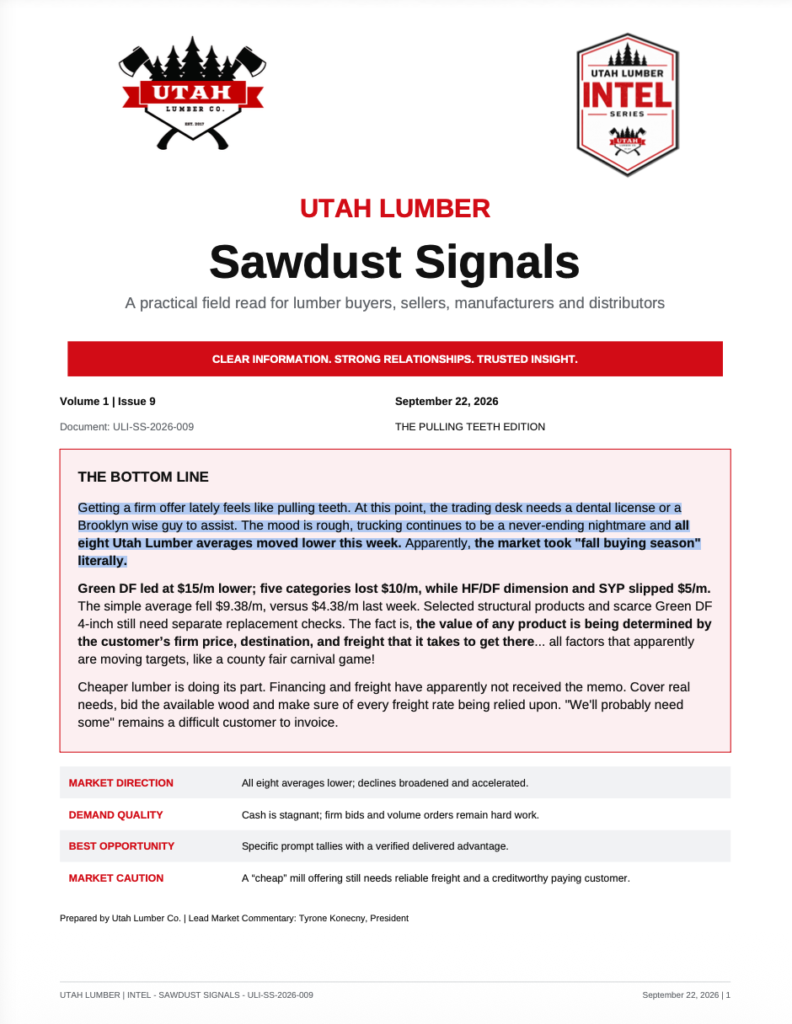
Welcome to the lumber showroom. Plenty of people checking the price tag, a few kicking the tires, and the firm
offer is apparently waiting in the car. Five Utah Lumber averages moved lower; WSPF, ESPF and Euro
held flat. That is an improvement from last week’s eight-for-eight decline. We will take it. Confetti is still subject
to credit approval.
Sawdust Signals – Vol. 1 Issue. 9 – The Pulling Teeth Edition
Getting a firm offer lately feels like pulling teeth. At this point, the trading desk needs a dental license or a
Brooklyn wise guy to assist. The mood is rough, trucking continues to be a never-ending nightmare and all
eight Utah Lumber averages moved lower this week. Apparently, the market took “fall buying season”
literally.
Sawdust Signals – Vol. 1 Issue. 8 – The Show-Me-The-Order Edition
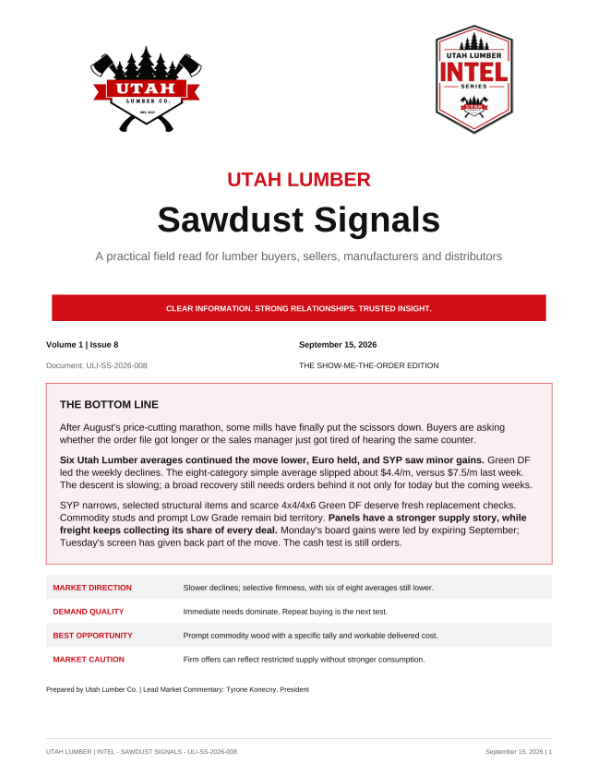
After August’s price-cutting marathon, some mills have finally put the scissors down. Buyers are asking
whether the order file got longer or the sales manager just got tired of hearing the same counter.
Six Utah Lumber averages continued the move lower, Euro held, and SYP saw minor gains. Green DF
led the weekly declines. The eight-category simple average slipped about $4.4/m, versus $7.5/m last week.
The descent is slowing; a broad recovery still needs orders behind it not only for today but the coming weeks.
[URGENT] Trade Bulletin – Special Alert – Freight Security
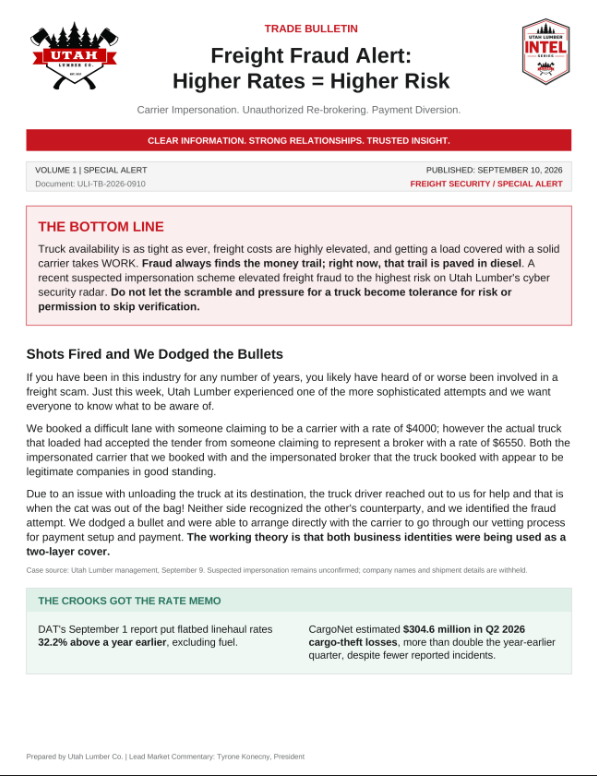
Truck availability is as tight as ever, freight costs are highly elevated, and getting a load covered with a solid
carrier takes WORK. Fraud always finds the money trail; right now, that trail is paved in diesel. A
recent suspected impersonation scheme elevated freight fraud to the highest risk on Utah Lumber’s cyber
security radar. Do not let the scramble and pressure for a truck become tolerance for risk or
permission to skip verification.
Sawdust Signals – Vol. 1 Issue. 7 – The Counteroffer Hangover Edition
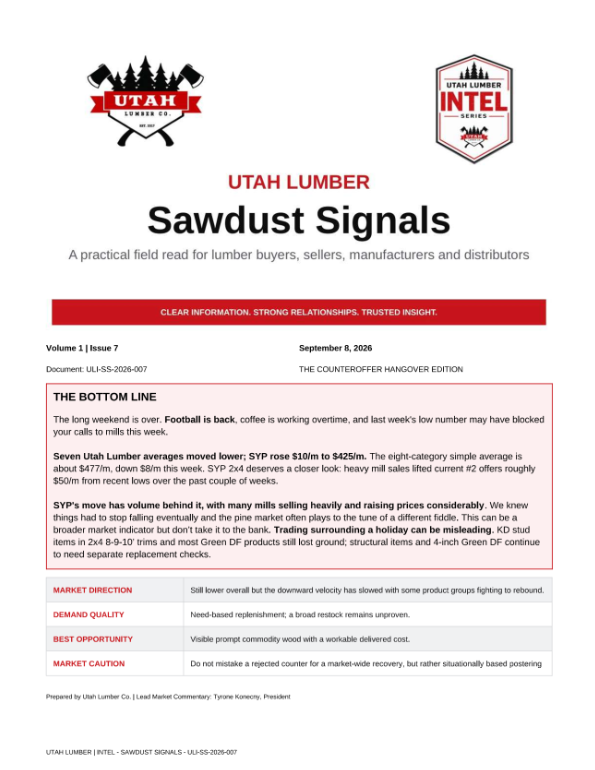
The long weekend is over. Football is back, coffee is working overtime, and last week’s low number may have blocked
your calls to mills this week.
Seven Utah Lumber averages moved lower; SYP rose $10/m to $425/m. The eight-category simple average is
about $477/m, down $8/m this week. SYP 2×4 deserves a closer look: heavy mill sales lifted current #2 offers roughly
$50/m from recent lows over the past couple of weeks.
Sawdust Signals – Vol. 1 Issue. 6 – The Clearance Aisle Edition
After several weeks of broad markdowns, the lumber market has become the least organized clearance sale in
recent memory. Plenty of signs say SALE; the exact tally you need may still be full price.
All eight Utah Lumber averages moved lower again. The eight-category average is now about $484/m, down
$15/m in one week and $69/m over four weeks. Low Grade is wearing the brightest red sticker – down another
$30/m this week and $95/m in four weeks. Other industry pricing publications reported little to no change in
economy, leaving many traders scratching their heads in disbelief.
Sawdust Signals – Vol. 1 Issue. 5 – The Counter Culture Edition
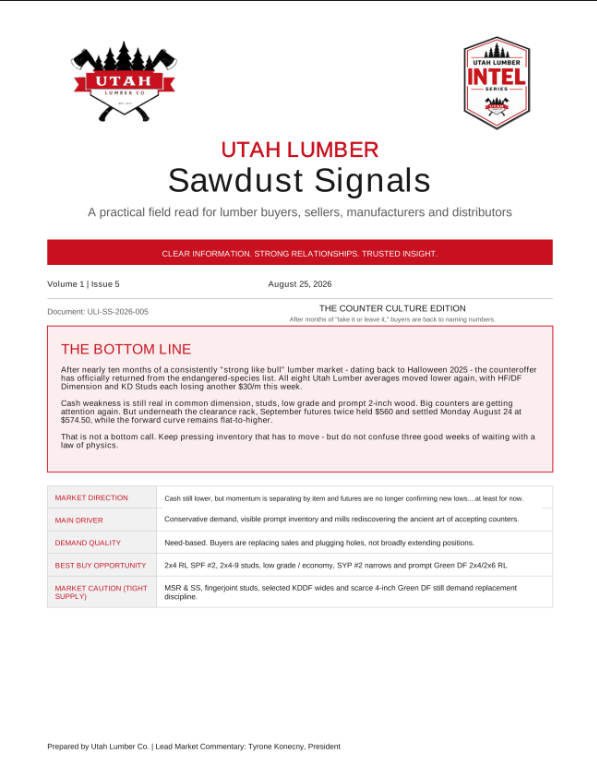
After nearly ten months of a consistently “strong like bull” lumber market – dating back to Halloween 2025 – the counteroffer
has officially returned from the endangered-species list. All eight Utah Lumber averages moved lower again, with HF/DF
Dimension and KD Studs each losing another $30/m this week.